Making a cash flow forecast: how it works
A cash flow forecast shows the expected receipts, payments and bank balance per week or month. That way you see in time whether you have enough money for rent, salaries and VAT. Profit is not the same as money in the bank: loan repayments, investments, stock and VAT count differently for cash than for profit.
By Redactie Nexora
What is a cash flow forecast?
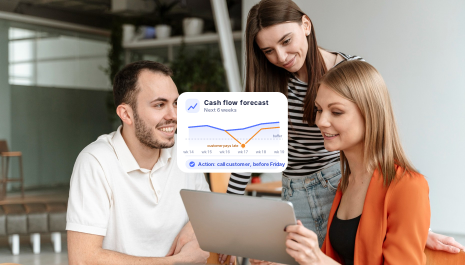
A cash flow forecast is an overview per week or per month with three lines: what you expect to receive, what you expect to pay and what will then be in the bank. You start from today's balance and calculate ahead.
That way you see weeks in advance whether the balance will get too low somewhere, for example when salaries and the VAT payment fall in the same week. Then you can still do something: call a customer, postpone a payment or arrange credit.
- Receipts: payments from customers, and for example a loan or a VAT refund.
- Payments: suppliers, rent, salaries, payroll taxes, VAT, loan repayments and investments.
- Balance: the balance of the previous period plus receipts minus payments.
How does it differ from profit?
Profit is not the same as money in the bank. Loan repayments, investments, stock and VAT count differently for cash than for profit:
- Loan repayment: not a cost, so profit does not change, but the money does leave your account.
- Investment: you pay for a machine in one go, but for profit you depreciate it over several years. That depreciation costs no money later on.
- Stock: what you bought and have not yet sold is money tied up. For profit it only counts when you sell it.
- VAT: does not count in your turnover or profit, but does pass through your cash: you receive it from customers and pay it to the tax authority later.
That is why a business can make a profit and still be short of cash, or make a loss and have money in the bank.
How do you enter receipts?
Enter receipts on the date customers are expected to pay, not on the invoice date. If you send an invoice on 1 March with a payment term of 30 days, put the receipt around 31 March. If a customer usually pays later, work with that experience.
- Use the payment term of each invoice and the customer's payment behaviour.
- Add expected revenue from quotes or the sales pipeline separately, with a cautious estimate.
- Put a VAT refund on the date you expect it.
How do you enter payments?
Enter fixed payments such as rent, salaries, payroll taxes and the VAT payment on the date they are paid.
- Rent: on the day the rent leaves your account.
- Salaries: the net wages on the day of payment.
- Payroll taxes: in the Netherlands by the last day of the month after the payroll tax period.
- VAT: by the last day of the month after the VAT period; with a quarterly return by 30 April, 31 July, 31 October and 31 January.
- Suppliers: on the due date of their invoices.
How often do you update it?
Update the cash flow forecast at least every month and compare it with what actually happened. If you were off, look at why: did a customer pay later, or was a cost higher? Take that into the next version.
If cash is tight, update it every week. Also keep a buffer for setbacks, such as a customer who does not pay on time.
Example: 't Groene Hart
Garden business 't Groene Hart has plenty of work and many open invoices, but by mid-April there is little in the bank. The owner makes a weekly forecast.
- The balance is €12,000. Customers pay the March invoices, €30,000 in total, only at the end of April according to the payment terms.
- At the end of April, salaries (€18,000), payroll taxes for March (€7,000) and VAT for the first quarter (€6,000) go out: €31,000 in total.
- If all customers pay on time, the balance afterwards is €12,000 + €30,000 − €31,000 = €11,000. If one customer with a €10,000 invoice pays late, it is €1,000.
The owner calls that customer to ask whether the invoice will be paid on time, and agrees with a supplier that one invoice may be paid a month later. That creates a buffer.
How it works in Nexora
In Nexora your open invoices, purchase invoices and bank come from the same administration. In Management & BI you see your cash position, and with forecasts and scenarios you calculate ahead: what a decision means for cash, revenue, capacity and margin before you take it.
- The figures come from the systems you work in, so you do not wait for the month-end close.
- For each KPI you set a target and an owner; a deviation becomes an action with an owner and a deadline.
- Nora prepares a draft report with the deviations and an explanation. You review and decide.
Read more about Management & BI in Nexora.
Frequently asked questions
What is the difference between profit and cash flow?
How often should I update my cash flow forecast?
Why do I need a buffer?
On what date do I enter customer payments?
On what date do I enter rent and salaries?
Business operations that think along with you.
Let us show you in 30 minutes where Nexora can create calm, control and momentum straight away.